Why Cash for Homes Offers a Straightforward Alternative to the Traditional Sale
Selling a house is rarely as simple as putting up a sign and waiting for offers. Most homeowners find that out pretty quickly. Even in a strong market, the gap between listing a property and actually closing can stretch into months. Repairs get negotiated, financing falls through, and the whole process leaves you wondering if there is a faster way. There is. The cash for homes model has grown into a real alternative for people who need certainty more than they need a bidding war.
I have watched this space evolve over the past decade. What started as a niche strategy for distressed properties has become a mainstream option. Companies like OpenDoor and WeBuyHouses brought the concept into the open, and now local investors and family-run firms operate alongside them. The idea is simple: a cash buyer looks at your property, makes an offer based on its current condition, and closes on your timeline. No staging, no open houses, no waiting on a buyer's mortgage approval.
Who Actually Uses This Route
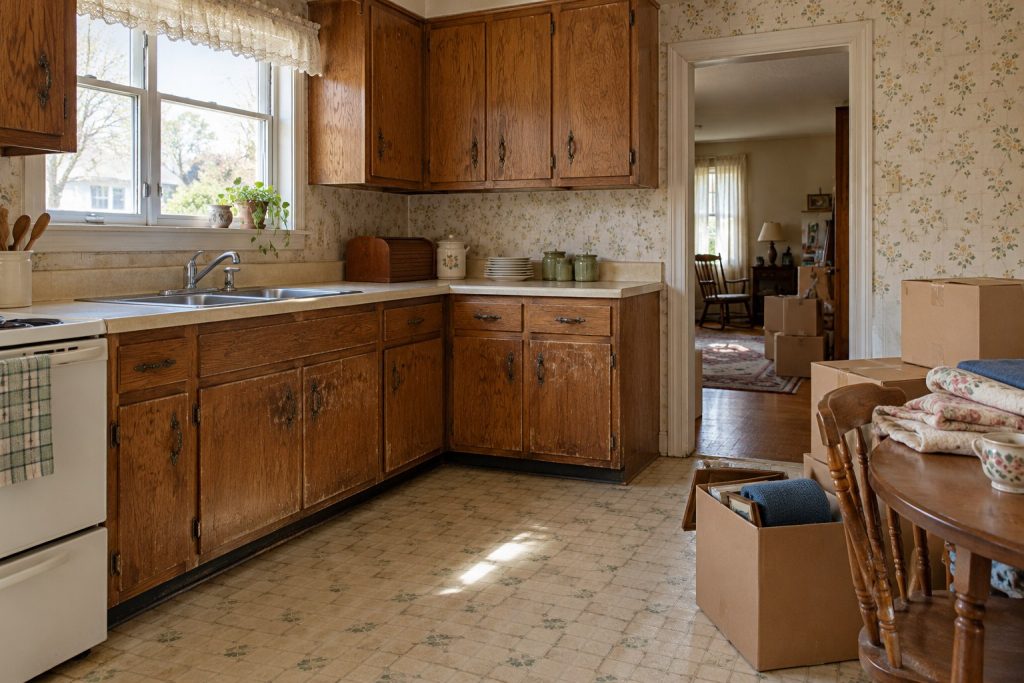
Most people assume cash for homes is only for houses that are falling apart. That is not really accurate. While many sellers do have properties that need serious work, plenty of others are just tired of the traditional process. I have worked with families who inherited a house from a parent and needed to settle the estate quickly. The house was in decent shape, but it sat in another state, and none of the siblings wanted to manage a renovation from a distance. A cash buyer handled the whole thing in three weeks.
Others face a different kind of pressure. A job relocation, a divorce, or a sudden medical bill can force a sale before the house is ready for the open market. In those cases, waiting for a traditional buyer to secure financing adds a layer of risk that many people cannot afford. The cash buyer removes that risk. The offer letter arrives without a financing contingency, and the title company can schedule the closing as soon as the paperwork clears.
The Role of Condition and Valuation
One of the biggest differences between a cash sale and a traditional listing is how the property gets valued. A realtor will usually price a house based on comparable sales, then adjust for condition after a home inspection. If the inspection turns up termite damage, an outdated roof, or a failing HVAC system, the buyer either walks or demands a price reduction. That can kill a deal two weeks before closing.
A cash buyer, by contrast, prices the house as-is from the start. They factor in the cost of repairs and the time it will take to resell the property. The offer might come in below what a perfect-condition house would fetch, but it is a real number that does not change after an inspector walks through. For a seller who does not have the money or the patience to fix things, that certainty is worth something real.
How It Differs from an iBuyer or OpenDoor
There is a difference between a local cash buyer and the big iBuyer platforms. OpenDoor and similar companies rely on algorithms to generate offers. They factor in local market data, recent sales, and their own renovation costs. The offer is often competitive, but the fee structure can eat into the proceeds. Some sellers find that the net amount they walk away with is not much different from what a traditional sale would have given them after commissions and closing costs.
A local cash buyer, on the other hand, may offer a lower gross number but fewer deductions. There is no service fee, no holding cost. The price you see on the offer letter is close to what you get at closing. The trade-off is that the buyer needs to see a profit margin on the resale, so the offer will reflect that. For a seller who values speed and simplicity, that trade makes sense.
Another difference is flexibility. A national iBuyer may only operate in certain zip codes and may decline properties that fall outside their risk model. A smaller cash buyer might handle a duplex with tenants, a house with a tax lien, or a property that has been sitting as an REO after a foreclosure. These are situations where a conventional lender would walk away, but a cash buyer with experience in distressed assets can still move forward.
The Paperwork Side of Things
Every real estate transaction involves a title search, a review of the deed, and a check for outstanding liens. In a cash sale, these steps still happen, but they happen faster. The buyer pays for the title work, and the title company coordinates with the county to clear any issues. If there is a tax lien or an unpaid HOA assessment, the buyer usually handles it out of the proceeds. The seller does not have to front the money to resolve those problems before closing.
Probate sales are another area where cash buyers add value. When someone dies without a clear will, the court has to approve the sale. Traditional buyers rarely want to wait for a court date. A cash buyer understands the timeline and works with the executor to get the deal done once the court gives the green light. The same goes for short sales, where the seller owes more than the house is worth. A cash buyer can negotiate directly with the bank because they are not asking for a loan.
FSBO and the For-Sale-by-Owner Crowd
Some sellers try FSBO first, thinking they will save the commission. They list on Zillow, hold a few open houses, and wait. What they often discover is that buyers who come without an agent still need a mortgage, and that mortgage brings an appraisal and a list of repair demands. By the time the FSBO seller has dealt with three failed deals, they are ready to talk to a cash buyer. I have seen this cycle repeat more times than I can count. The FSBO route works when the house is in perfect condition and priced below market. For everyone else, cash for homes becomes the safety net.
When It Makes Sense to Go the Traditional Route
I am not arguing that cash is always better. If your house is in move-in condition and you are not in a hurry, listing with a local realtor and waiting for the right buyer can net you a higher price. The competitive dynamics of an open market can push the final sale number above the initial asking price. That is harder to replicate in a cash deal because the buyer is taking on risk and needs to protect their margin.
There is also the FHA 203(k) option for buyers who want to purchase a fixer-upper and roll the renovation costs into the mortgage. That program helps traditional buyers compete with cash offers, but it adds weeks to the closing timeline. If you are selling to someone using a 203(k) loan, you are back to waiting on appraisals and government approvals. For a seller who needs to close in thirty days, that is not a realistic path.
Practical Advice for Sellers
If you are thinking about selling to a cash buyer, do a little homework first. Get a rough idea of your home's value by looking at recent sales in your neighborhood on Zillow or asking a local realtor for a quick opinion. That gives you a benchmark. When the cash buyer's offer letter arrives, you will know whether it is reasonable or lowball.
Ask the buyer for proof of funds. A legitimate cash buyer should have a bank statement or a letter from a financial institution showing they have the money to close. If they cannot produce that, move on. Also ask about the timeline. Some cash buyers want to close in ten days. Others give you thirty or forty days to move out. Pick the one that fits your situation.
Be clear on what the buyer is paying for. Are they covering the closing costs? Are they handling the title search? Are they willing to pay for a survey if the property lines are unclear? Get those details in writing before you sign anything. A good cash buyer will be transparent about all of it. A bad one will dodge the questions.
The Bigger Picture
The real estate market has changed a lot since the days when every sale went through a realtor and a bank. Companies like HUD homes and REO departments proved that institutional buyers could move volume, and now individual investors and small firms have adopted the same methods. The iBuyer model brought technology into the mix, but the core idea remains the same: people who need to sell quickly should have a option that does not require them to fix a leaking roof or wait for a stranger's loan approval.
Cash for homes is not a magic bullet. It is a tool, and like any tool, it works best when you match it to the job. If your house needs work, if your timeline is tight, or if you just want to avoid the headache of showings and negotiations, it is worth exploring. Just go in with your eyes open, compare offers, and do not be afraid to ask hard questions. The right buyer will answer them.